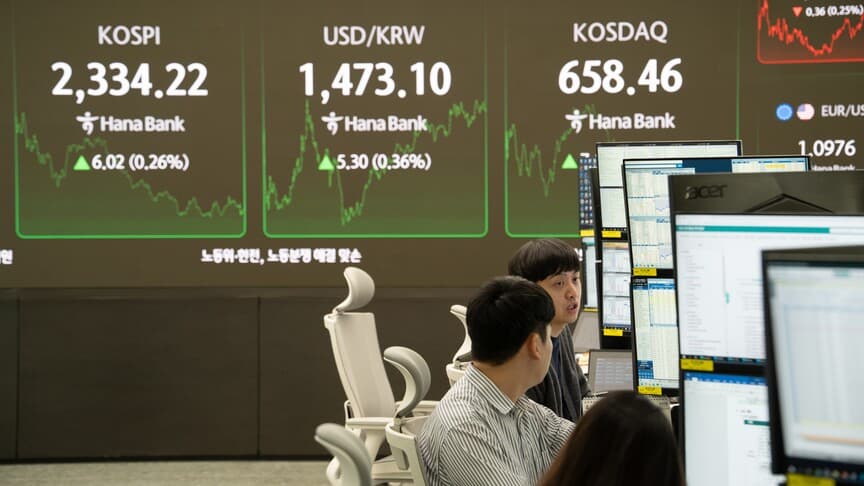
Technology stocks in Asia rose on Tuesday following a Wall Street rally triggered by Anthropic's IPO filing. The main gains came in Seoul and Tokyo, while other markets showed mixed performance. Investors are awaiting earnings from Microsoft, Alphabet and Amazon, as well as the Fed's decision.
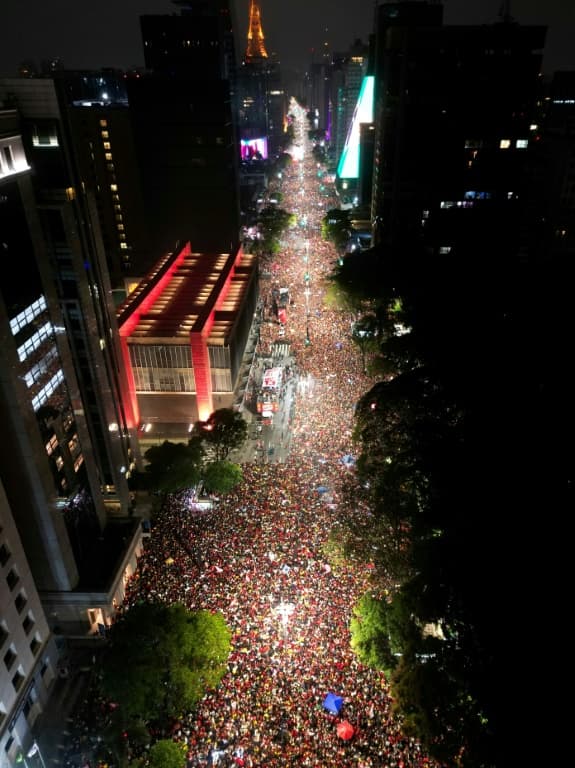
Lula da Silva has been re-elected president of Brazil, receiving more than 64.2 million votes — 4.4 million more than his rival Flavio Bolsonaro. Bolsonaro refused to concede defeat and demanded the annulment of the election over the two-hour extension of voting. World leaders congratulated Lula, but Donald Trump has so far remained silent; Brazilian markets fell by almost 17%.
After Lula da Silva's unexpected victory in the runoff election, the Brazilian real and the Sao Paulo stock market fell sharply, though part of the losses was recovered by the close. Other markets focused on tech companies' earnings and central bank decisions.
According to Anadolu, the week ending October 23 closed with declines in US and European indices, and Monday opened mixed. Markets are under pressure from doubts about the returns on AI investments, geopolitical risks surrounding the US and Iran, and weak consumption data. Investors' attention is focused on decisions by the Fed, the ECB and the Bank of Japan. According to Anadolu, the week starting October 23 ended with declines in US and European indices, and Monday opened mixed. Markets are under pressure from doubts about the return on AI investments, geopolitical risks surrounding the US and Iran, and weak consumption data. Investor attention is focused on the decisions of the Federal Reserve, the ECB and the Bank of Japan.
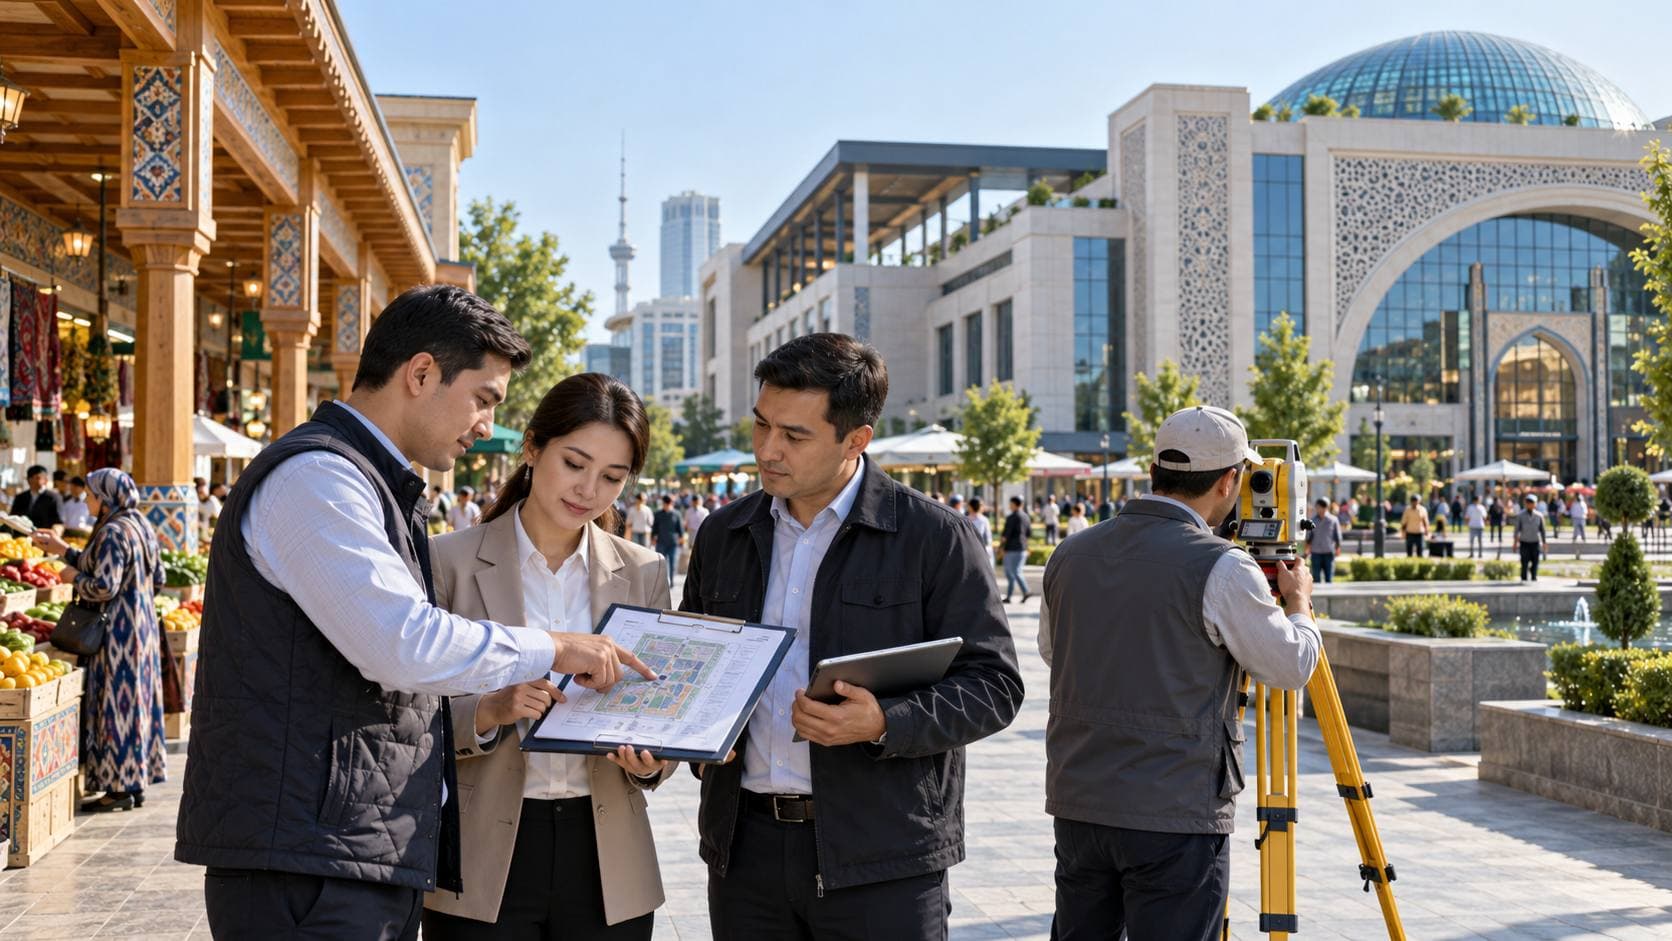
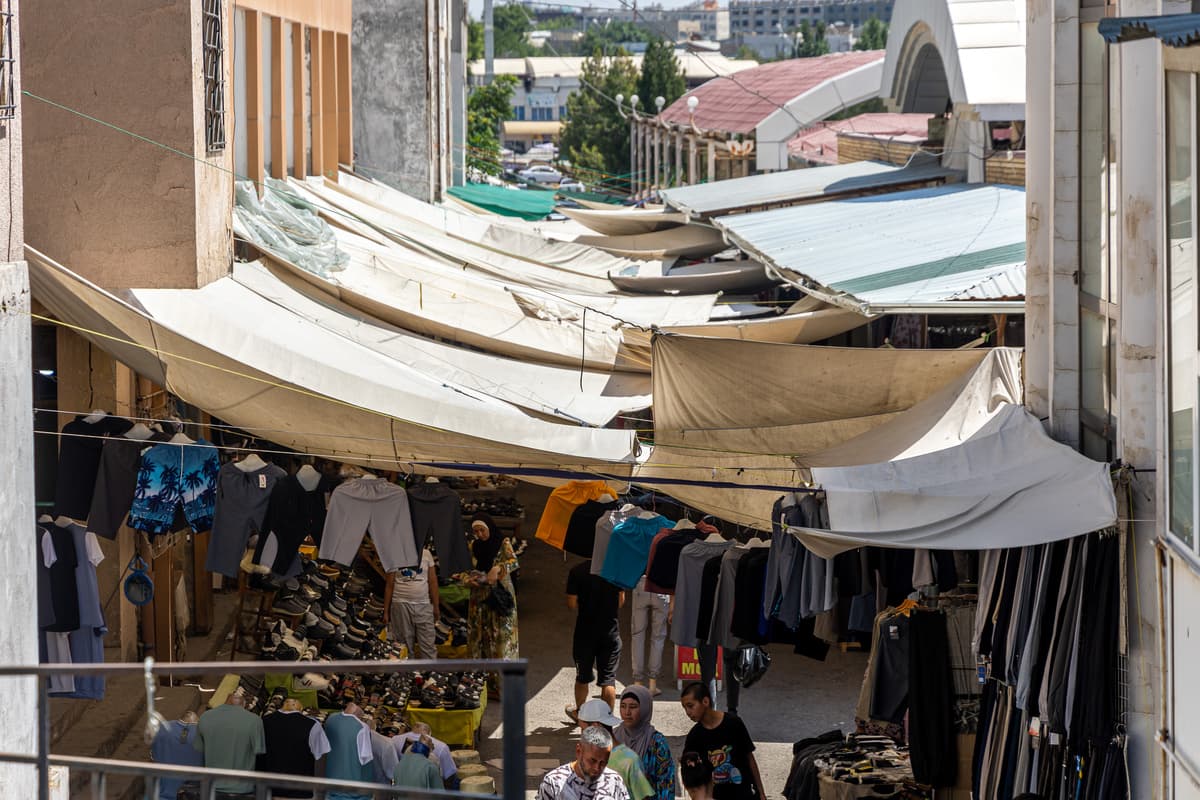
The Tashkent city administration (khokimiyat) reported that, as part of additional measures for the city's socio-economic development for 2026–2027, a review of the financial condition of markets and shopping complexes, an inventory of their property and identification of existing problems will be organized. The process will examine cadastral documents, owner registers, illegal constructions, land plot boundaries and the complexes' debts. Based on the results, proposals will be prepared, including the possible sale of assets at public auction.
US markets closed higher on Wednesday, but Asian trading began with a selloff on Thursday amid Middle East tensions and doubts about the returns on AI investments. Brent rose to $110.7 per barrel, and French 10-year bond yields exceeded 5%. Meta reported net profit growth of 264%, Tesla a decline of 43%.
The Tashkent khokimiyat reported that, as part of measures for the socio-economic development of the capital in 2026–2027, the financial condition of markets and trade complexes will be studied, an inventory of their property will be conducted, illegal structures and debts will be identified. Based on the results, proposals will be prepared, including the possible listing of assets for public auction.
Monday brought a recovery in global markets: US Treasury yields fell, gold rose, and US indices opened higher. Support came from optimism around a new Middle East peace plan and China's Q3 GDP data (+4.5%). European indices, however, opened lower amid protests in France, while the Nikkei 225 fell after statements by Prime Minister Takaichi.
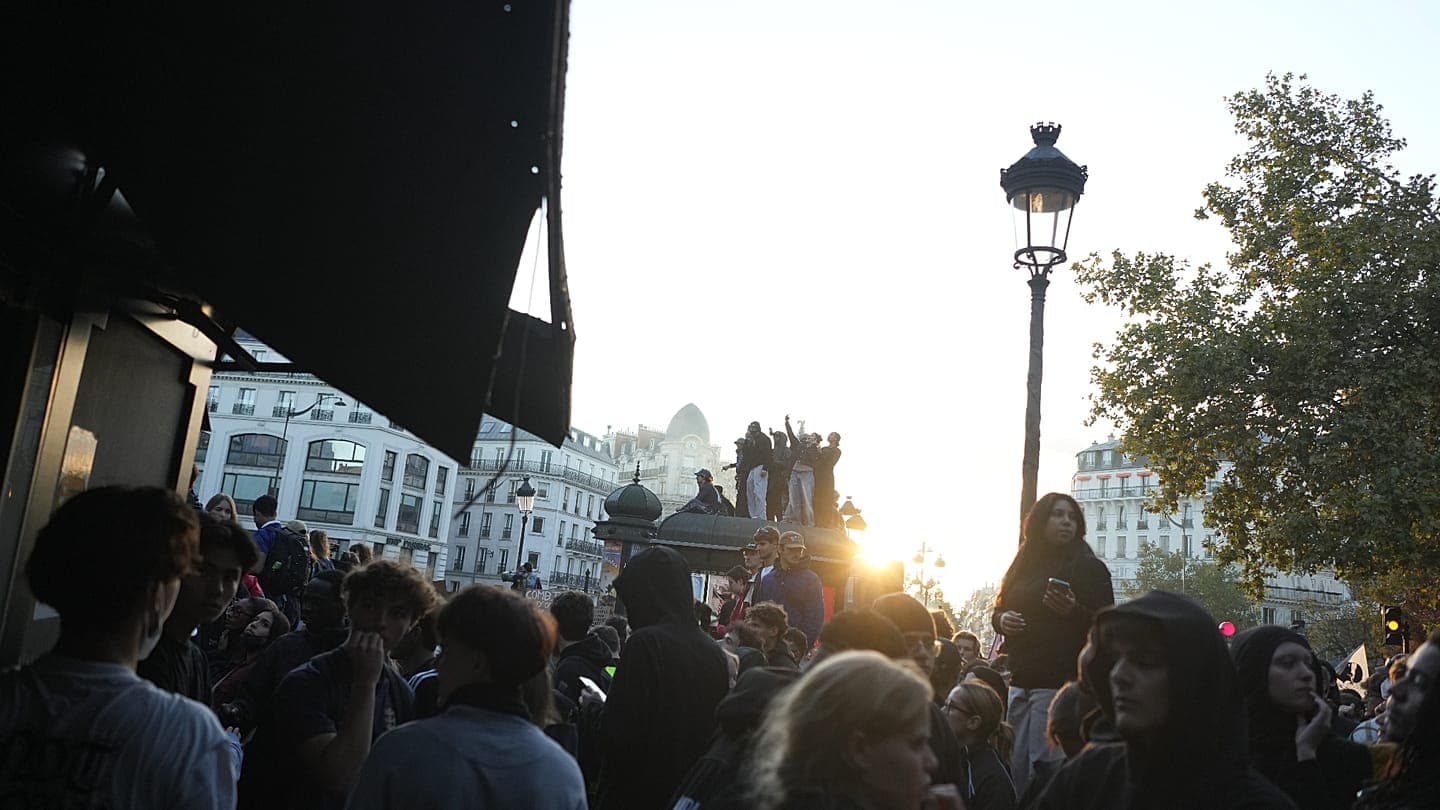
Over the weekend, thousands of people took to the streets of European cities against rising prices, expensive housing and low wages. In France, some actions escalated into riots with damage amounting to hundreds of millions of euros, and Macron promised to hold those responsible to account. Markets reacted with falling indices.
On Thursday, global markets traded positively: technology stocks recovered after the previous day's decline, and US Treasury yields fell. US PPI in September rose 1.3% month-on-month and 6.3% year-on-year — the highest since 2022 — reinforcing concerns about a possible Fed rate hike. Retail sales beat expectations (+0.8%). Asian indices rose notably, while European and American ones were mostly in positive territory.
Oil prices rose in morning trading on Wednesday following Reuters reports of Iran attacking two vessels in the Strait of Hormuz. Brent surpassed $107 per barrel, WTI reached $94.64. The Houthi-Saudi Arabia conflict added supply risks: an attack on an Aramco building caused a 'limited fire', and debris from intercepted rockets injured four people in Riyadh. European TTF gas futures hit a four-year high, European indices opened higher, and Asian trading was mixed.