The key facts
- Rheinmetall cut its 2026 revenue guidance to ~€13.2 billion (from €13.7–14.2 billion) and its margin to 18.5% from 19%
- Shares fell more than 17% by 10:00 CET on November 5; they have lost over 48% since the start of the year
- At the same time, Q3 operating profit rose 62% to €553 million, and over nine months it reached a record €1.339 billion
Forecast cut due to orders being pushed to 2027
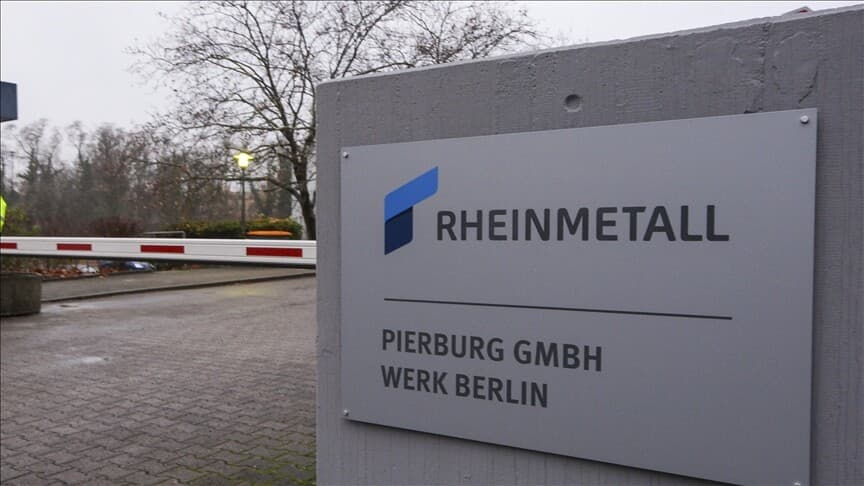
Shares of the Düsseldorf-based defense group Rheinmetall AG fell by more than 17% on November 5 as of 10:00 CET after the company lowered its 2026 guidance on Wednesday evening. Expected revenue was revised down to approximately €13.2 billion from the previous €13.7–14.2 billion, and the operating margin to 18.5% from 19%. This was reported by Anadolu and euronews.
Reasons: Arminius, ammunition and Destinus
The main reason is a delay in a major Bundeswehr order under the Arminius project, which provides for the procurement of Boxer wheeled armored vehicles produced by Rheinmetall and the KNDS group. According to the company's estimate, the contract will not be placed this year, so advance payments and the associated revenue are being shifted to 2027. An additional factor is delays in acceptance inspections of artillery ammunition batches, which also push revenue into next year. In addition, revenues expected in 2026 from new business lines will not materialize, primarily cooperation with the Dutch company Destinus. Because of the deferral of Arminius advance payments, the previous cash flow target is also at risk: management had counted on a cash flow conversion above 40%, but it still expects a positive operating free cash flow for the year.
Second cut of the year despite record results
As euronews notes, this is already the second cut to the 2026 sales guidance: in August the company revised it after Germany cancelled the F126 frigate program, which reduced expected annual revenue by €300 million; the margin was left unchanged at that time. Notably, the guidance cut is not linked to falling demand: in the third quarter, sales grew 32% to €3.149 billion, operating profit rose 62% to €553 million, and over nine months profit reached a record €1.339 billion (up 69%). Order intake amounted to €2.893 billion — a level the company called good, though somewhat lower. CEO Armin Papperger emphasized that the order backlog supports capacity expansion, including the launch of production at new facilities in the United Kingdom and Spain.
Pressure across the whole sector and analysts' reaction
The decline also affected other European defense companies: at around 10:00 CET BAE Systems was down more than 4%, Leonardo 2.8%, Saab 2.7%, Babcock 1.3% and Thales 0.9%. Selling intensified after Wednesday's drop amid concerns about tighter oversight of US military spending following the Democrats' election victory: Vertical Research Partners analyst Robert Stallard, as quoted by MarketWatch, predicts increased congressional scrutiny of defense policy. JPMorgan lowered its price target for Rheinmetall shares from €1,350 to €1,150 while keeping a 'neutral' rating; analyst David Perry questioned the long-term sales prospects of some army products and warned that the company may have to revise its 2030 targets. Since the beginning of the year, the group's shares have lost more than 48%, partially giving back the sharp growth of the previous three years.