The key facts
- The Agency for State Asset Management has developed a concept for privatizing the 100% stake of the plant owned by Uzbekneftegaz; no timeline or stake for investors was named
- Remaining principal debt on loans is $838.2 million as of June 16, 2026; Russian loans have been fully repaid
- The plant reached full capacity only in December 2025; at the trial of former Uzbekneftegaz management, more than 2,400 defects were mentioned
Preparation for privatization and IPO
Preparation for the privatization of the Uzbekistan GTL plant has begun in Uzbekistan. The head of the Agency for State Asset Management (AUGA), Sokhibzhon Murodov, spoke about the progress of the process at a press conference on October 8. According to him, the privatization concept has been developed and preparatory work is underway: assessment of financial and economic activities, identification of problems, and analysis of the consequences of a change of ownership. He explained that the privatization deadline indicated in the documents means the start of work, not a mandatory sale by that date. Before the sale, an audit must be conducted and the impact of the deal on the economy, raw material suppliers, partners, and product buyers must be assessed. Under a presidential decree of April 21, 2025, the 100% stake of the plant owned by Uzbekneftegaz is subject to privatization: preparation was planned from the third quarter of 2025, public tenders from the second quarter of 2026, but by October the enterprise had not yet been put up for sale. At the same time, AUGA is preparing a possible IPO: Murodov said that major international organizations had approached with a question about participation. The parameters of the privatization, the stake for investors, and the timing of the IPO were not named. When asked about the plant's financial condition and repaid debt, the head of AUGA did not provide data, promising to disclose the figures via the agency's social media.
The plant and its loans
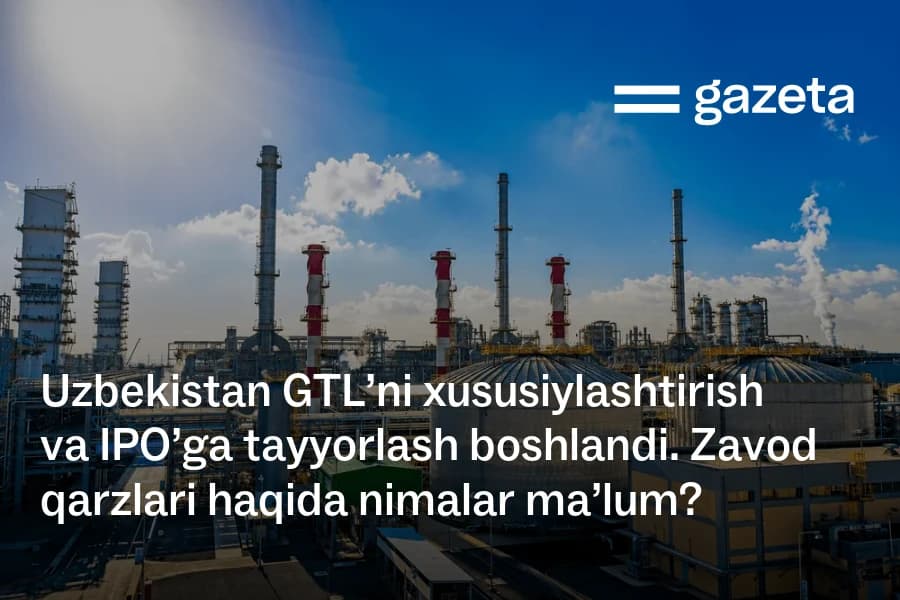
Uzbekistan GTL is located in the Kashkadarya region next to the Shurtan gas chemical complex; President Shavkat Mirziyoyev launched it in December 2021. The plant uses gas-to-liquids technology: its design capacity is processing 3.6 billion cubic meters of gas per year, producing 724 thousand tons of diesel fuel, 307 thousand tons of aviation kerosene, 437 thousand tons of naphtha, and 53 thousand tons of liquefied gas. Construction cost $3.42 billion, of which about $2.3 billion was financed by foreign loans under state guarantees. According to the plant's official website, as of June 16, 2026, the remaining principal debt was $838.2 million — about $1.46 billion, or 63.6% of the original amount, has been repaid. The largest creditor is the China Development Bank ($483.6 million out of $1.2 billion). The Export-Import Bank of Korea accounts for $201.5 million, loans with K-SURE insurance coverage for $112.8 million, and those under a KEXIM guarantee for $40.3 million. Loans from Russian banks have been fully repaid: the debt to Gazprombank ($120 million) and the RosEximBank loan it bought out ($100 million) were closed early on February 28, 2023. In 2025, the creditor structure changed: the Singapore branch of KEB Hana Bank bought out part of the debt under a KEXIM guarantee and $30 million under K-SURE, while the London branch of MUFG Bank bought the remaining claims of Credit Suisse, which had been absorbed into UBS. It is noted that this amount reflects only the principal debt and not necessarily all obligations, including interest; the construction cost is not equal to the market valuation or the privatization price, which have not been disclosed.
Problems voiced in court
In July 2026, a trial began in Tashkent against the former chairman of the board of Uzbekneftegaz, Bakhodirzhon Sidikov, and eight other people; one of the episodes is related to obligations to the American company Air Products under the GTL project. At the hearing on July 31, Sidikov said that after construction more than 2,400 defects were identified, about 50 of them critical, on the three main units, including the air separation equipment. According to him, because of this the plant operated at roughly 72% of capacity, and failure to meet the indicators of credit agreements created a risk of early repayment of about $2.4 billion, which, with a state guarantee, could fall on the budget. To solve the problems, Air Products was brought in, agreeing to finance the elimination of defects with subsequent reimbursement of costs by the contractor Enter Engineering; former deputy head of Uzbekneftegaz Bakhtiyar Anarkulov clarified that the amount in question was about $56 million for repairs over three years. A separate dispute concerns a payment of approximately $21.4–21.8 million that Uzbekneftegaz transferred to Air Products on behalf of the contractor under a suretyship. Sidikov stated that the payments were needed to preserve the project and investor confidence; the defendants did not admit guilt. In August, the case was moved to closed proceedings.
The Air Products deal and reaching capacity
In May 2023, the government of Uzbekistan and Uzbekneftegaz signed a $1 billion agreement with Air Products: the American company acquired the industrial gas production facilities (air separation units, synthesis gas and hydrogen equipment), ensures their operation, and supplies gases to the plant. According to Air Products' reporting, the agreement is designed for 15 years with a fixed monthly fee regardless of consumption volume; the Uzbek side has the right to buy the facilities back after the term ends. The deal is accounted for as a financial transaction: as of September 30, 2025, the corresponding receivable was about $1 billion. In December 2025, Uzbekneftegaz announced that the plant had reached full capacity four years after launch. Chairman of the board Abdugani Sanginov criticized the long-standing problems: technological shortcomings had not been fully eliminated, and emergency shutdowns continued. Management ordered an analysis of the causes of the shutdowns, elimination of risks, an increase in production by 15–20% in 2026, and the search for additional gas sources without reducing supplies to domestic consumers. The debt burden and underutilization of the plant had previously attracted the attention of rating agencies: at the end of 2023, S&P downgraded Uzbekneftegaz's rating from BB− to B+, and in 2025 improved it again. Before privatization, questions remain open regarding current profitability, the full structure of obligations, operational stability, and the terms of the sale.