The key facts
- Experts believe mass valuation is suitable for taxes but not for compensations and collateral
- An example was cited: neighboring palace-like house and dilapidated house received almost the same valuation
- The proposal is to retain individual valuation for transactions and guarantee the owner an independent report
One valuation for different purposes?
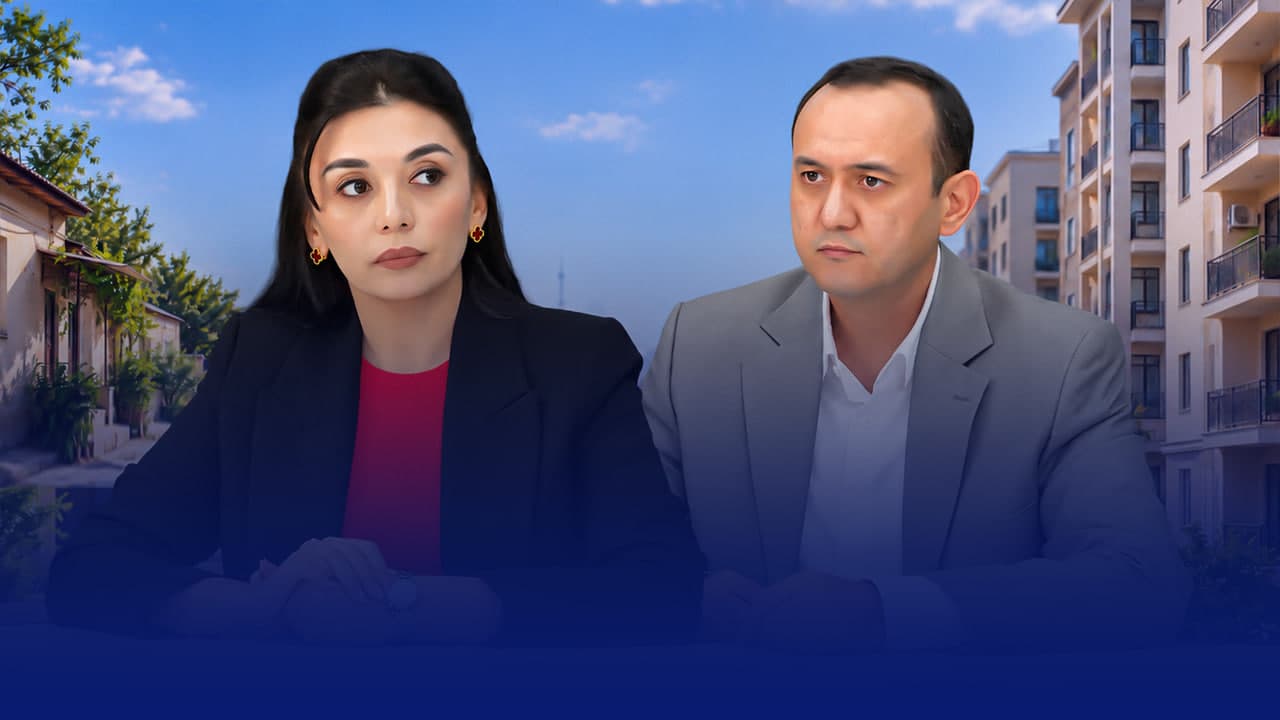
In Tashkent, owners are asked to review the value of their housing determined during the mass valuation and express their opinion. At the same time, it remains unclear for what purposes this figure will be used in the future and how it will affect the interests of owners. Kun.uz previously discussed the topic with the leadership of the National Center for Mass Real Estate Valuation, and this time the interlocutors were the chairwoman of the Appraisers Society of Uzbekistan Zebuniso Isanova and a member of its board Shukhrat Abduvakhobov, who voiced objections to the approaches in the draft law.
Risk for owners and banks
According to Isanova, the result of a mass valuation cannot be equated to an individual valuation of a specific house: the requirements for the calculation depend on the purpose. She opposes the automatic application of a value determined for the tax base in sale and purchase, collateral or expropriation for public needs. She also noted that the concept of 'close to market value' used in the draft requires legal clarification — a new term does not replace the requirement to determine market value. Abduvakhobov explained: in mass valuation, similar objects are grouped and the value is derived from generalized indicators, whereas for collateral or compensation it is necessary to evaluate an individual object and its features. An undervalued figure benefits the owner for tax purposes, but if the same figure becomes the basis of compensation upon expropriation, the owner risks receiving less than the real value of the property; an overvalued valuation, on the contrary, may harm the payer of the compensation. The expert believes that before requesting consent, a citizen should be explained for what purposes the result will be used: an owner may agree with the same amount from a tax point of view and disagree from a compensation point of view.
A palace and ruins with one price
Isanova cited an example studied by the society: two neighboring houses — one resembling a palace, the other in very poor condition — received almost the same value in the mass valuation. In an individual valuation, the technical condition and other characteristics must be reflected in the calculation. Abduvakhobov said that in a methodology familiar to him, if the cadastre contains data on the condition of repairs, they are used, and if absent, the condition is considered average; such an approach may insufficiently reflect the difference between renovated houses and those requiring renovation. He also objected to floor coefficients: in his example, for a five-story building, a downward coefficient was assigned to the first floor and an upward coefficient to the fourth and fifth floors, which, in his opinion, may not correspond to the real market given buildings without elevators and the commercial potential of the first floor. Isanova emphasized the significance of these differences for banks: if an object requiring major renovation is valued as qualitatively renovated, the collateral security may be unreasonably overstated, and in case of loan default the collateral may not cover the debt.
Compensations and experts' proposals
The issue of compensation is not limited to the condition of the house. According to Abduvakhobov, reliance on the cadastral database may leave some outbuildings or long-standing trees unaccounted for. He noted that the law on expropriation of land for public needs provides for compensation of the market value of real estate, land rights and trees, as well as, in cases provided by law, compensation for structures not entered into the cadastre; covering objects missing from the database through mass calculation is difficult. Isanova added that underestimating compensation looks like savings in the short term, but disputes with the owner, revaluation, litigation costs and project delays may cost more, and such a situation undermines trust in the protection of property rights. Both experts proposed limiting the task of mass valuation to forming a base value for tax purposes, retaining individual valuation for compensations, collateral and other individual transactions, and clearly enshrining in law the right of a disagreeing owner to defend their interests through an independent report.