The key facts
- Dow rose 1.0% to 52,495.88 amid rotation out of tech; Nasdaq slipped slightly
- Brent fell 0.7% to $108.79 after comments about continuing US-Iran talks
- Kospi lost 3.7% in a selloff of chip giants; French-German bond spread at widest since 2011
Rotation out of tech stocks lifted the Dow
US stocks mostly rose on October 20, 2026, on falling oil prices and a flow of funds into industrial stocks amid continued caution about artificial intelligence stocks. The Dow index gained more than 1%, largely thanks to strong earnings from industrial company 3M, closing at 52,495.88 (+1.0%). The S&P 500 rose 0.3% to 7,712.57, while the Nasdaq Composite slipped less than 0.1% to 26,424.82. Briefing.com analyst Patrick O'Hare characterized the Dow's rise as a 'rotation' out of technology stocks, noting continued weakness in the AI segment, which kept the rally from becoming fully broad-based.
Oil fell on news of US-Iran talks
Oil prices declined after comments by Qatari Foreign Ministry spokesman Majed al-Ansari that US-Iran talks are 'ongoing,' although there were no concrete changes in the conflict that has disrupted energy supplies for more than seven months. Brent futures closed down 0.7% at $108.79 per barrel, after earlier rising to $111.99. West Texas Intermediate fell 1.8% to $101.79. In addition, Saudi Arabia on Monday postponed a major investment conference due to repeated attacks by Iran-backed Yemeni Houthis.
AI profitability concerns weigh on the tech sector
Technology stocks have shown volatility recently: analysts point to concerns about AI profitability and the significant debt financing of some companies. The sector is also vulnerable after outperforming the market for most of 2026. According to O'Hare, there is nervousness that growth rates may not be as strong as assumed: 'there may be genuinely good news, but it may not be enough to justify high expectations.'
Asian markets hit by chip stock selloff
Earlier, AI concerns hit Asian exchanges. Seoul and Tokyo again bore the brunt: chip giants SK hynix, Samsung and Kioxia suffered amid a sharp exit from a sector that had shown explosive growth in the first half of the year. The Kospi index fell nearly 4% (final figure: 3.7% to 5,552.74), with SK hynix losing 4.2% and Samsung 3%. Additional pressure came from data center infrastructure company Elice, whose shares plunged more than 30% on their trading debut. The Nikkei 225 fell 1.3% to 64,075.52, the Hang Seng fell 1.3% to 23,867.74, while the Shanghai Composite gained 0.1% to 3,735.37.
Protests in Europe push bond yields higher
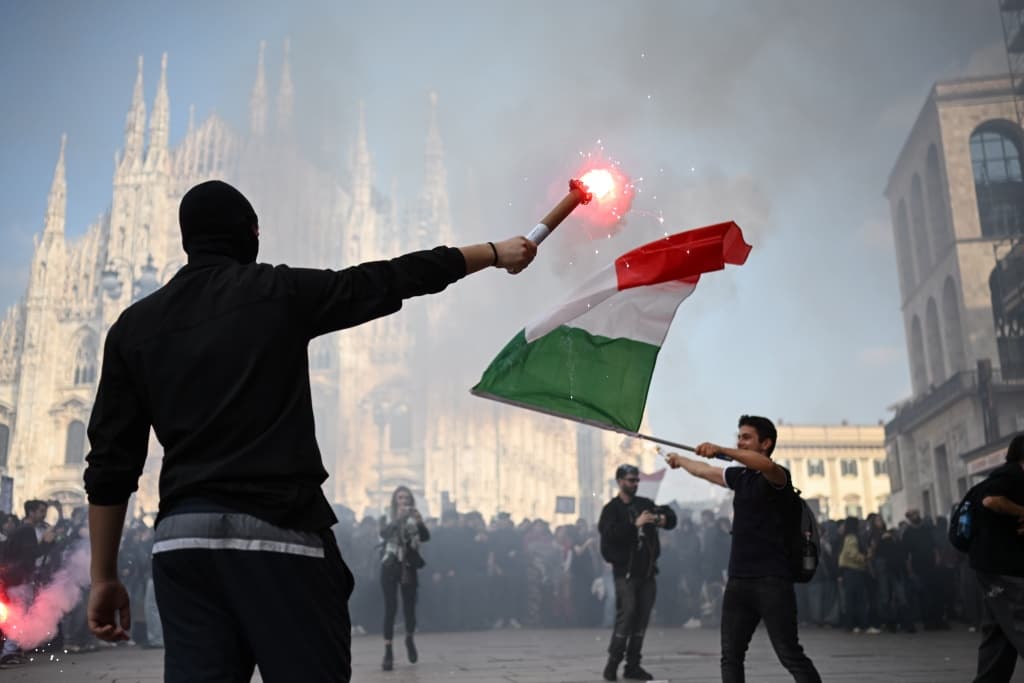
Negative sentiment spilled over into European trading. The euro rose against the dollar but remained under pressure: mass protests in France and Italy are pushing up government bond yields. The yield on ten-year French bonds reached 4.94% on Tuesday, more than 150 basis points above comparable German bonds, considered Europe's benchmark of creditworthiness. The spread between them reached its highest level since 2011. The FTSE 100 fell 0.3% to 10,733.00, the CAC 40 fell 0.4% to 7,838.49, and the DAX slipped less than 0.1% to 25,304.42.
GM falls despite better-than-expected earnings
General Motors shares tumbled 6.8% despite earnings that beat expectations: the automaker pointed to a recent rise in commodity prices due to the US-Iran war, which clouds its earnings outlook. On currency markets, the euro rose to $1.1235 from $1.1213, the pound rose to $1.3378 from $1.3305, the dollar fell to 158.23 yen from 158.50, and the euro slipped to 83.98 pence from 84.26.